
By Eurohoops team / info@eurohoops.net
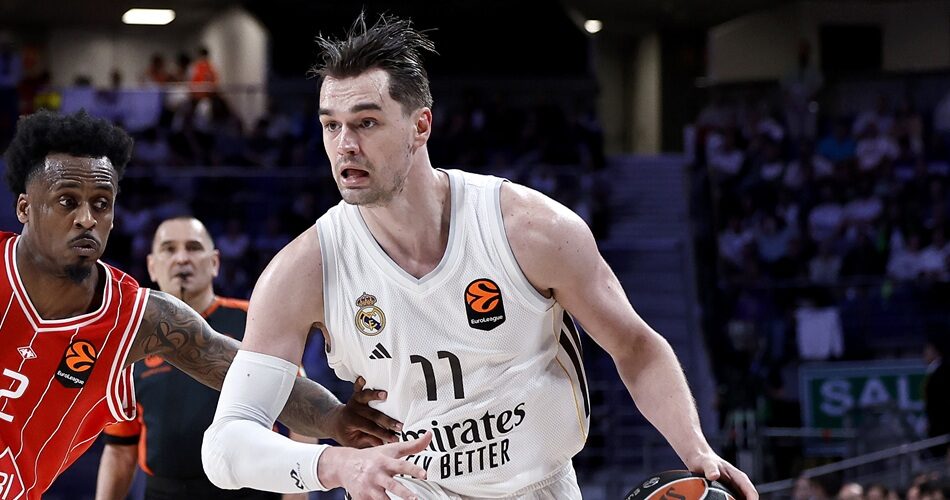
When his NBA out clause started making headlines this summer, Mario Hezonja said something that should change how every EuroLeague bettor thinks about futures markets: “This is something very common that I believe a lot of players have. It’s extra on the contract; it doesn’t mean that it’s necessarily happening. Even last year, I went upstairs and shut it down.”
Read that again. The Liga Endesa MVP and top scorer of a EuroLeague finalist had a serious NBA offer just before the playoffs last season, and the only thing that kept him in Europe was his own decision. Every futures bet placed on Real Madrid last season was, whether the bettor knew it or not, also a bet on Hezonja saying no. This summer, he said yes. The way it unfolded is a lesson every EuroLeague bettor should study.
How NBA Exit Clauses Actually Work
Hezonja’s contract with Real Madrid runs until 2029. On paper, that looks like long-term security. In practice, the deal contains an NBA out clause valid until July 20 of each offseason for the length of the contract, with a buyout of approximately $850,000 – described by BasketNews as the standard figure for international players crossing the Atlantic. Set that number against multi-million-euro annual salaries, and it becomes clear how low the barrier actually is. For an NBA team seeking a EuroLeague star, the buyout is a rounding error.
The clauses are one-directional. Hezonja’s contract permits an exit only to the NBA, not to another European club. If the NBA move collapses, the player remains where he is. The windows are typically limited to the summer and close in mid-to-late July, before the European season begins. Crucially, the decision belongs entirely to the player. The club cannot block a properly exercised clause.
What all of this means is simple: a EuroLeague star with an NBA out is under contract in name but on a season-by-season commitment in practice. The multi-year deal is real until each July, when it briefly becomes optional.
What This Means for Futures Betting
Real Madrid entered this summer as beaten finalists, priced at 15/2 in the early 2026-27 title market. Hezonja was their offensive centrepiece — his 44 points at the Final Four were the highest individual output of the entire weekend. His departure to Cleveland on a one-year, $2.8 million deal removes much of the production that justified that price. The odds compilers can adjust after the departure. The bettor who took 15/2 in early July cannot.
Comparing prices across the market requires another layer of caution. Readers familiar with UK casino sister sites will know that several consumer-facing brands can operate under the same wider ownership, platform or commercial infrastructure. A similar principle applies when checking EuroLeague futures: identical odds displayed across related betting brands may reflect one underlying trading view rather than several independent assessments. Seeing Real Madrid at 15/2 in multiple places does not necessarily mean that several separate markets have correctly priced the risk surrounding Hezonja’s contract.
This is the structural problem that European futures betting has and NBA futures betting does not. In the NBA, guaranteed contracts generally mean a team’s core is locked when the futures market opens. In Europe, the market opens before the clause windows close. The gap between odds being published and exit windows expiring is a period in which every bet on a clause-carrying roster contains hidden risk that the price may not reflect.
You are not just betting on how a team will perform. You are betting on whether the roster you evaluated will still exist in October.
The reverse case matters equally. Jean Montero turned down a €10 million offer this summer because, in his words, he always knew he wanted Olympiacos. Sasha Vezenkov has committed to the club long-term. Teams whose stars have publicly closed the door on departures carry less clause risk, a stability factor the market does not explicitly price and which may quietly favour the teams at the top of the current odds.
The Hezonja Timeline – A Case Study in Uncertainty
What makes this summer’s saga so instructive is how messy it became and how long the uncertainty lasted. Hezonja informed Real Madrid of his intention to exercise the clause at the eleventh hour of his window, without an NBA deal in place. Since the clause could not be used to join another European club, a collapsed NBA move would have left him as a Real Madrid player.
According to Marca, the proper procedure was not followed, which handed negotiating leverage back to the club. Hezonja, confident in his NBA prospects, had already rejected offers from three EuroLeague teams to sign conditional contracts that would have activated only if his American return ended early.
The Cleveland agreement was not confirmed by his agent until July 26, six days after his clause window closed. Two days later, the move was still being held up by an exit-clause dispute, with Real Madrid pushing back on his release.
Theories circulated that he could sign an NBA minimum deal, be cut before the EuroLeague season and then return to Europe. NBA sources dismissed the idea, arguing that the league would not permit a bridge arrangement that could damage its image, particularly with the NBA Europe project in development.
Through all of this, nearly three weeks of genuine uncertainty about where the Final Four’s top scorer would play, Real Madrid’s title price remained at 15/2. The odds had to be expressed as a single number. The reality was a probability distribution spread across two continents.
That gap between the number and the reality is exactly where betting risk lives.
How to Read a Roster Like a Bettor
The good news is that this risk can be checked, and the checks take only a few minutes.
First, follow the clause reporting. Outlets covering the EuroLeague transfer market routinely report which contracts contain NBA outs. Hezonja’s clause had been public knowledge for years before he used it. The information was freely available before any futures bet was placed.
Second, watch the window dates. Most NBA out clauses expire in mid-to-late July. A futures bet placed in August carries structurally less roster risk than the identical bet at the identical price placed in early July.
Third, listen to the player. Hezonja negotiated an NBA exit clause into his contract because returning to the league had been his stated goal for years. A player who keeps the American door open in every interview presents a different risk from one who publicly closes it, as Montero did.
Fourth, consider age and career stage. Hezonja is 31. This summer was likely to be one of his final realistic opportunities to return to the NBA, which increased the probability that he would take it. A 24-year-old with the same clause may have several future summers and less urgency in any single one.
Finally, remember that the European side is only half of the equation. Hezonja’s move reportedly depended in part on Cleveland’s situation with LeBron James. European clause risk is entangled with NBA roster mechanics that many European bettors do not follow. That is precisely why those who do follow them may have an edge.
Every EuroLeague futures bet is two bets: one on the team and another on the contracts holding it together. The Hezonja saga made that visible for three weeks this summer. The same risk exists every summer, usually less visibly.
The bettors who read the clauses are betting on the roster that will actually take the floor in October. Everyone else is betting on a photograph of a roster that may already be dissolving.
Make  Your Preferred Basketball Source.
 Add Eurohoops to Google